Understanding Offshore Corporate Banking: Legality, CRS Transparency, and the Modern Regulatory Reality
Opening a bank account for an offshore company requires matching your business model with institutional risk appetites, providing authenticated Ultimate Beneficial Owner (UBO) records, and proving direct commercial nexus. Tier-1 commercial banks approve accounts based on total source-of-funds clarity and automated tax transparency rather than physical entity incorporation location alone.
International corporate banking operates under stringent cross-border regulatory frameworks. Shell companies with anonymous owners face immediate rejection by modern risk desks.
The global rollout of automatic financial data sharing under OECD CRS regulations and FATCA rules has made account transparency mandatory. Banks must know the exact tax residencies of all controlling persons before assigning a multi-currency business account.
“International banking institutions evaluate non-resident cross-border structures through regulatory transparency, tracing every operational transaction back to verified commercial counterparties.”
— Senior Risk Review Officer, Asian Compliance Advisory
Legitimate tax optimization differs sharply from unlawful evasion. Holding companies incorporated in regions like the British Virgin Islands (BVI) or Cayman Islands remain legal structures for asset management and international trade.
However, securing active bank routing requires substantial documentation. Banks evaluate operational logic, management background, and verifiable customer bases to prevent financial crime.
The 5S Banking Eligibility Evaluation Framework: How Banks Score Offshore Applicants
Based on our multi-year corporate registration and treasury management data across international hubs, traditional financial institutions grade cross-border applicants against a stringent multi-vector matrix. We evaluate institutional bankability through our proprietary Olesen 5S Bankability Architecture:
- Substance (Corporate Presence): Physical operations, dedicated local directorship, lease agreements, and domestic commercial activities.
- Structure (Ownership Clarity): Direct, unencumbered corporate shareholding charts free of opaque, multi-layered nominal shields.
- Source of Funds (Capital Provenance): Audited historical bank statements, investment liquidation records, or clear seed funding documentation.
- Settlement Patterns (Counterparty Quality): Verified suppliers, reputable institutional clients, and absence of sanctioned corridors.
- Supervisory Alignment (Jurisdictional Legitimacy): Companies incorporated in recognized regulatory environments with accessible registries and clear tax filings.
For example, an offshore trade intermediary operating without verifiable physical lease agreements or full-time staff must demonstrate strong supply chain contracts. When applying for Corporate Bank Account Opening, presenting pre-vetted corporate dossiers directly satisfies compliance requirements under anti-money laundering AML verification frameworks.
Mandatory Documentation Checklist: From Certificate of Incumbency to Counterpart KYC
Document deficiencies trigger over 60% of international banking rejections. Non-resident corporate applicants must present statutory, corporate, and operational verification records authenticated by a registered professional.
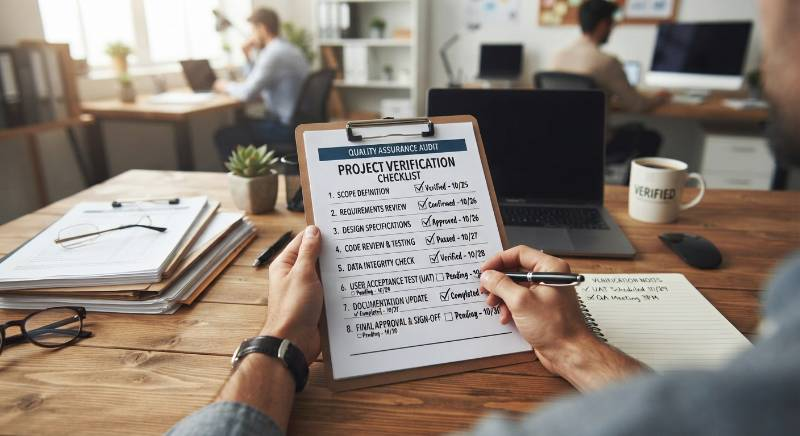
- Certificate of Incumbency: Issued within the last 3 to 6 months by the registered agent, listing all current directors and shareholders.
- Certificate of Good Standing: Required for offshore entities incorporated over 12 months prior.
- UBO Identification: Certified true copies of international passports, residential utility proofs (under 90 days), and CVs showing professional background.
- Operational Proof: Minimum of 2 signed sales contracts and 2 corresponding supplier purchase orders with valid invoices.
- Transactional Evidence: 6 months of historical corporate bank statements from existing accounts or personal director statements showing liquidity.
- Corporate Governance: Formal board resolution authorizing account opening and establishing authorized signatories.
Compliance teams strictly review substance and physical presence requirements to ensure trading companies are not empty conduit vehicles. Aligning your statutory records through certified Company Secretary Services provides verified document custody before submitting your application to international relationship managers.
Jurisdiction Comparison: Hong Kong vs. Singapore vs. Switzerland for Offshore Entities
Selecting the right banking jurisdiction determines your available multi-currency clearing networks, average account maintenance costs, and capital efficiency. Global corporate banking hubs balance distinct compliance standards and deposit minimums.
| Jurisdiction | Initial Deposit Baseline | Remote Onboarding Feasibility | FX & Capital Flow Controls | Average Review Timeline |
|---|---|---|---|---|
| Hong Kong | $1,200 – $10,000 USD | High (via TCSP digital channels) | Zero controls; free convertibility | 2 – 4 Weeks |
| Singapore | $30,000 – $100,000 SGD | Moderate (Director visit often required) | Zero controls; strict screening | 4 – 8 Weeks |
| Switzerland | $250,000 – $1,000,000 CHF | High (Video identity verification) | Zero controls; high custody fees | 3 – 6 Weeks |
Hong Kong stands out as an efficient, highly accessible gateway for global trading entities. Supervised under the Hong Kong Monetary Authority (HKMA), international institutions in Hong Kong offer dedicated multi-currency settlement systems spanning USD, EUR, GBP, and CNH without exchange control barriers.
For cross-border operators requiring rapid access to regional capital, establishing a parent entity via Hong Kong Company Registration creates a strong foundation for long-term global banking relationships.
Tier-1 Commercial Banks vs. Digital Virtual Banks: Strategic Architecture for Cross-Border Cash Flow
Modern cross-border treasury management often combines tier-1 institutional clearing banks with regulated virtual banking platforms. This hybrid approach helps ensure consistent transaction processing.
| Evaluation Dimension | Tier-1 Commercial Banks (e.g., HSBC, Standard Chartered) | Digital Virtual Banks (e.g., ZA Bank, Airwallex) |
|---|---|---|
| Cross-Border Fund Settlement | Direct global SWIFT BIC routing; trade letters of credit (LC) | API-driven local clearing rails; virtual IBAN networks |
| Corporate KYC Compliance Onboarding | Comprehensive in-person or high-tier video vetting; 3-4 weeks | Rapid electronic verification; 3-7 business days |
| Counterparty Trust Level | Highest rating for enterprise, state-owned, and institutional partners | Ideal for e-commerce payouts, software, and vendor disbursements |
| Transaction Limits | Virtually unlimited based on validated revenue history | Tiered monthly transaction and transfer ceilings |
Established institutions like HSBC Commercial Banking and Standard Chartered Bank provide essential corporate credibility, long-term trade finance, and international treasury stability. Virtual accounts offer agile clearing rails for high-frequency, smaller transactions across diverse global payment processors.
High-Risk and Emerging Sectors: Securing Bank Accounts for Web3, E-Commerce, and Consulting Entities
Certain industries encounter enhanced compliance reviews during onboarding. Non-resident structures operating in high-scrutiny sectors require specialized compliance packaging before submitting applications to bank underwriters.
Web3 and Blockchain Startups
For a Web3 startup operating in Cyberport or Hong Kong Science Park, banks conduct strict reviews of token utility, smart contract security audits, fiat ramps, and non-custodial transaction flows. Onboarding requires showing segregated client funds, verified algorithmic business models, and formal compliance legal opinions.
Cross-Border E-Commerce Enterprises
For an Amazon, Shopify, or TikTok Shop cross-border merchant, compliance reviews focus on store ownership proofs, merchant payout records, intellectual property ownership, and supplier payment terms. Underwriters assess inventory turnover and return-rate data to rule out credit default or consumer fraud risks.
International Consulting and Advisory Vehicles
Service-based offshore firms often find it harder to prove physical assets or tangible product shipments. Applicants must provide detailed milestone service agreements, professional engagement letters, time-logs, and verifiable director credentials to demonstrate operational legitimacy.
Step-by-Step Roadmap: Applying for an Offshore Bank Account with First-Hand TCSP Pre-Screening
Direct applications by non-resident founders face high rejection rates due to formatting errors or ambiguous risk profiles. Working with a registered TCSP licensed provider helps ensure your corporate documentation is fully vetted before submission.
- Pre-Evaluation & Risk Mapping: Initial review of shareholding structures, target business sectors, projected monthly transaction volumes, and transaction counterparties.
- Dossier Assembly & Certification: Drafting director resolutions, notarizing passports, and obtaining certified true copies of statutory certificates under TCSP oversight.
- Pre-Screening Review: Submitting pre-application files directly to commercial compliance managers to address potential underwriting queries early.
- Banker Interview & Identity Verification: Completing biometric eKYC digital identity verification or visiting an international banking center.
- Compliance Clearance & Account Activation: Receiving bank details, making the initial activation deposit, and configuring multi-currency corporate online banking.
Using experienced bank account opening support simplifies the onboarding process and prevents formal rejections that could complicate future international applications.
Acing the Banker Interview: Essential Q&A Preparation and Red Flag Avoidance
The relationship manager interview serves as a critical compliance checkpoint. Clear, accurate answers help establish commercial credibility during the review process.
“Underwriters reject applications when founders struggle to explain why their offshore entity chose a specific jurisdiction, or when operational descriptions differ from the submitted company business plan.”
— Senior Corporate Onboarding Specialist, Olesen Global
- Why did you incorporate in this specific jurisdiction? Clarify commercial reasons—such as regional market access, proximity to manufacturers, multi-currency settlement needs, or access to international investors.
- What is your projected annual turnover? State clear, realistic numbers aligned with your operational proofs. Do not inflate figures beyond your documented capacity.
- Who are your key clients and suppliers? Name established corporate counterparties and specify their primary operating countries.
- Red Flags to Avoid: Mentioning sanctioned regions, vague personal cash handling, or using unverified third-party personal accounts for settlement.
Post-Opening Account Maintenance: Preventing Dormancy, Managing Annual Audits, and FSIE Compliance
Maintaining an active international corporate bank account requires ongoing compliance. Accounts with irregular activity or missing records risk unexpected freezing or administrative review.
Under regulations from the Hong Kong Inland Revenue Department (IRD), companies claiming tax exemptions must comply with strict Foreign Sourced Income Exemption (FSIE) rules. Entities must demonstrate clear economic substance, adequate local expenditure, and proper management records.
Maintaining valid status across global banking networks requires completing regular Accounting & Audit Services. Delivering clean annual audited reports during periodic KYC updates ensures uninterrupted access to international payment rails.
Offshore Corporate Banking Statistics and Industry Approval Trends
Recent compliance reviews across tier-1 banking institutions highlight shifting patterns in corporate account approvals and onboarding requirements:
- Direct Application Friction: Unassisted non-resident applications across top-tier international hubs currently see a 72% rejection rate due to missing documentation or unexplained corporate structures.
- Pre-Screened Acceptance: Applications pre-screened by a licensed TCSP achieve an approval rate above 92% across major commercial institutions.
- Processing Timelines: Digital eKYC and modern compliance systems have brought average onboarding times down to 14 to 21 business days, compared to historical 8-to-12 week cycles.
- Periodic Review Frequency: Over 88% of major international commercial banks now run automated annual or bi-annual transaction monitoring on offshore entity accounts.
Frequently Asked Questions: Offshore Corporate Banking
Can a 100% foreign-owned offshore company open a Hong Kong bank account remotely?
Yes. Through licensed TCSP intermediaries and bank-integrated digital channels, directors can complete video verification and digital eKYC protocols remotely without traveling in person.
What is the minimum initial deposit required for an offshore corporate account?
Deposit requirements vary by institution. Hong Kong commercial banks typically require between $1,200 and $10,000 USD, while European private banks may require higher initial balances.
Can I open an account for a BVI, Cayman, or Seychelles entity in Hong Kong?
Yes. Hong Kong banks regularly onboard BVI, Cayman, and other international entities provided you present a recent Certificate of Incumbency, Certificate of Good Standing, and proof of legitimate business operations.
Why do banks reject offshore company applications without giving a specific reason?
Under international anti-tipping-off rules, banks are restricted from sharing internal compliance findings. Rejections typically stem from unverified beneficial owners, missing operational proofs, or higher-risk counterparty locations.
Secure Guaranteed Pre-Approval for Your Offshore Corporate Account with Olesen Global
Avoid bank application rejections. As a first-hand licensed Trust or Company Service Provider (TCSP License TC010076), Olesen Global provides 1-on-1 dossier pre-screening, direct tier-1 banking matching, and end-to-end onboarding support.