The 2026 Corporate Tax Evaluation Framework: Beyond Nominal Rates
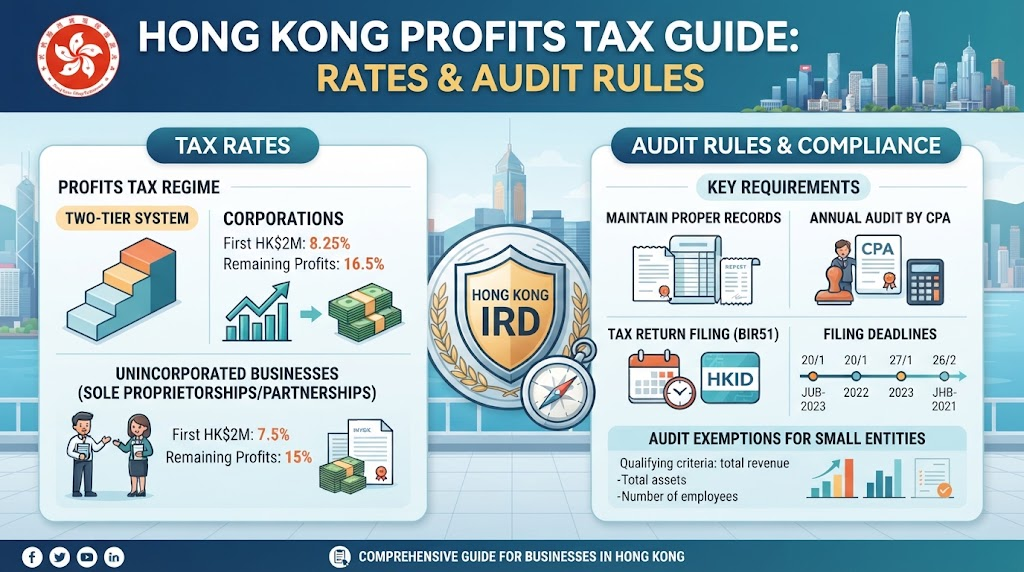
Hong Kong profits tax liability for corporations is calculated at 8.25% on the first HKD 2,000,000 of assessable profits and 16.5% thereafter under the two-tiered regime. Statutory compliance under the Inland Revenue Ordinance (Cap. 112) mandates that every active corporate taxpayer substantiate its tax calculations using independent financial statements audited by a qualified Hong Kong CPA.
Navigating cross-border corporate taxation in Hong Kong requires looking past surface-level headline rates. Businesses must adopt a rigorous compliance model to withstand intensified data-matching by international tax authorities and the Inland Revenue Department (Hong Kong).
“A company’s effective tax rate in Hong Kong is meaningless if its underlying audit substantiation cannot survive an IRD Section 51 inquiry or an economic substance review under updated international standards.”
— HKICPA Practicing Certified Public Accountant, Technical Advisory Council
To eliminate compliance ambiguity, corporate directors should measure their tax risk exposure against The Tri-Vector Corporate Tax Governance Framework:
- Audit Substantiation Robustness: Complete synchronization between primary bank records, contractual agreements, and accounting ledgers certified by an independent auditor.
- Offshore Claim Legality: Defensible documentation meeting the refined Foreign Sourced Income Exemption (FSIE) regulations and Departmental Interpretation and Practice Notes (DIPN 21).
- Direct TCSP & CPA Accountability: Direct engagement with licensed corporate service providers and Hong Kong Institute of Certified Public Accountants (HKICPA) firms, removing intermediary operational failure.
Hong Kong Profits Tax Structure & Rates: Two-Tiered Regime Rules
Hong Kong enforces a territorial system of corporate income taxation. Profits tax is levied exclusively on assessable net profits arising in or derived from a trade, profession, or business carried on in Hong Kong.
Under the two-tiered profits tax rates regime, tax burdens are systematically discounted for small and medium-sized enterprises (SMEs) without requiring complex corporate structuring:
| Entity Classification | First HKD 2,000,000 Profits | Profits Above HKD 2,000,000 | Statutory Audit Requirement |
|---|---|---|---|
| Corporations (Limited by Shares) | 8.25% | 16.5% | Mandatory (Cap. 622) |
| Unincorporated Entities (Partnerships/Sole Proprietors) | 7.5% | 15.0% | Certified Accounts Only |
| Connected Corporate Entities (Nominated Only) | 8.25% (Single entity in group) | 16.5% | Mandatory (Cap. 622) |
| Connected Corporate Entities (Non-Nominated) | 16.5% (Full rate from dollar one) | 16.5% | Mandatory (Cap. 622) |
A corporate enterprise generating exactly HKD 2,000,000 in assessable profits saves HKD 165,000 each tax year under the two-tiered regime compared to the baseline 16.5% rate. There are no capital gains taxes, dividend withholding taxes, or goods and services taxes (GST/VAT) in Hong Kong.
Connected Entities Tax Election Modeling & Allocation Strategies
To prevent multi-entity enterprise groups from splitting income across multiple companies to multiply the 8.25% tax benefit, the IRD enforces strict anti-fragmentation rules under Section 14D of Cap. 112.
If an enterprise controls more than one Hong Kong entity, only one nominated entity within the group is eligible to elect for the 8.25% rate during a given year of assessment.
- Statutory Definition of Control: An entity is connected if one entity has direct or indirect control over the other (greater than 50% voting rights, share capital, or board appointment authority), or if both are under common control by the same parent entity or individual.
- The Allocation Strategy: The group must model annual net assessable profits across all Hong Kong subsidiaries. The 8.25% election form must be assigned to the subsidiary that reaches or surpasses the HKD 2,000,000 threshold first to capture the full HKD 165,000 tax relief.
- Formal Declaration: The nomination is finalized inside the statutory Profits Tax Return (BIR51). Once submitted for that assessment year, the election is irrevocable without special IRD authorization.
Setting up your corporate structure correctly starts during Hong Kong Company Registration to ensure your corporate umbrella is fully optimized for downstream tax filings.
Statutory Annual CPA Audit Requirements Under Companies Ordinance Cap. 622
Section 429 of the Companies Registry (Hong Kong) Ordinance (Cap. 622) legally obligates directors to present audited financial statements at every Annual General Meeting (AGM).
The IRD does not accept self-compiled internal balance sheets or unverified management accounts for limited liability companies. Every tax submission must be accompanied by audited accounts signed off by an independent Hong Kong Certified Public Accountant (Practicing) registered with the Hong Kong Institute of Certified Public Accountants (HKICPA).
- Director Fiduciary Accountability: Company directors carry personal civil and criminal liability for failing to maintain sufficient accounting records that explain transactions and disclose financial position with reasonable accuracy.
- Accounting vs. Auditing Separation: Compiling books (general ledgers, income statements) is distinct from performing a statutory audit. The statutory audit tests transaction reality, inventory validation, revenue recognition, and counterparty authenticity.
- Document Retention Standards: Under Section 51C of Cap. 112, all business records, invoices, bank statements, and vouchers must be retained for at least 7 years from the transaction date.
Zero Tax Return (零申报) vs. Statutory CPA Audit: Penalties & Fraud Risks
Some unlicensed offshore incorporation brokers advise foreign business owners to file a “Zero Tax Return” (or 零申报) to save on professional accounting and audit fees. If the company maintained an open bank account with cash inflows or signed commercial contracts during the basis period, filing a zero return is illegal.
“Submitting a nil tax return for an operating Hong Kong company is not a cost-saving loophole. It is treated as willful tax evasion under Section 82 of the Inland Revenue Ordinance.”
— Senior Compliance Director, Olesen Global
The legal and practical consequences of fraudulent zero tax declarations include:
- Financial Penalties: Fines under Section 80(2) up to HKD 10,000, plus a compounding treble tax assessment (up to 300% of the tax undercharged).
- Criminal Indictment: Directors face prosecution under Cap. 112 Section 82, carrying prison sentences up to 3 years.
- Immediate Banking Termination: Commercial banks in Hong Kong regularly share transaction volume logs with regulatory systems. Discrepancies between bank turnover and IRD tax returns trigger immediate frozen accounts and liquidation demands.
Using legitimate Hong Kong Accounting & Statutory Audit Services guarantees statutory defense while keeping corporate banking operations active.
Inland Revenue Department (IRD) Mandatory E-Filing Updates & Deadlines
The IRD has modernized corporate tax submissions, transitioning toward comprehensive mandatory e-filing for Profits Tax Returns alongside required iXBRL-formatted financial statements and tax computations.
Corporate directors must track the standard statutory compliance timeline:
- First Profits Tax Return (BIR51): Automatically issued by the IRD approximately 18 months after the date of company incorporation. The return must be completed and submitted within 3 months from the issue date.
- Subsequent Annual Tax Returns: Issued on the first working day of April each year. The default submission deadline is 1 month from the date of issue.
- Block Extension Scheme: Companies that appoint a recognized corporate tax representative can take advantage of the official IRD Block Extension Scheme based on their accounting financial year-end date:
- “N” Code (Year-end between April 1 and November 30): Submission deadline extended to April 30 of the following year.
- “D” Code (Year-end between December 1 and December 31): Submission deadline extended from April 30 to August 15.
- “M” Code (Year-end between January 1 and March 31): Submission deadline extended from April 30 to November 15.
Working alongside professional Hong Kong Company Secretary Services ensures that your annual AGM filings, statutory records, and tax extension windows are filed on time.
2026 Foreign Sourced Income Exemption (FSIE) & Offshore Claim Defense
The Hong Kong tax framework is built around the Territorial Source Principle of Taxation. If an enterprise’s profits do not originate in Hong Kong, they are not subject to profits tax. However, asserting an offshore non-taxable claim requires clear evidence.
Hong Kong’s refined Foreign Sourced Income Exemption (FSIE) framework enforces strict economic substance requirements for multi-jurisdictional groups receiving foreign passive income (dividends, interest, intellectual property income, and asset disposal gains):
| Income Classification | Core Substance Requirement | Key Substantiation Documents | Offshore Exemption Rate |
|---|---|---|---|
| Active Trading Income (Import/Export/Drop-shipping) | Operations, contracting, and customer negotiations conducted wholly outside HK. | Travel stamps, signed overseas contracts, logistics shipping orders, email logs. | 0% Assessable Tax |
| Passive Dividends & Equity Gains (FSIE) | Adequate qualified staff and operational spending in HK, or meeting participation rules. | Board resolutions, local operating expense ledgers, corporate registry filings. | 0% (Subject to Nexus/Substance) |
| Intellectual Property (IP) Income (FSIE) | Compliance with the OECD-compliant Nexus approach (qualifying R&D expenditures). | R&D cost tracking, patent ownership papers, lab outsourcing contracts. | Nexus-calculated Exemption |
Audit Trail Preparation & IRD Query Defense Checklist
When you file an offshore profit claim, the IRD will issue detailed query letters asking for documentation on how business operations were handled. Use this readiness checklist before submitting your return:
- Counterparty Trade Documentation: Fully signed sales and purchase contracts, purchase orders (POs), and order acknowledgments proving execution occurred outside Hong Kong.
- Logistical Audit Chain: Complete Bills of Lading (BL), airway bills, customs declarations, and third-party warehouse receipts showing goods never entered Hong Kong territory.
- Commercial Communication Records: Unbroken email trails, digital negotiation logs, and CRM records highlighting supplier sourcing outside Hong Kong.
- Banking & Settlement Continuity: Cross-referenced bank statement lines matching commercial sales invoices without cash-pooling commingling.
- Director & Management Presence: Proof that key strategic decisions, board meetings, and operational directions were managed outside Hong Kong.
Tailored Compliance for Web3, Cross-Border E-Commerce & Tech Ventures
International digital businesses operating through Hong Kong face specific audit complexities that generic accounting workflows often mishandle.
Modern online business structures require specialized accounting controls:
- Web3 & Crypto Asset Audits: Digital asset investments and treasury reserves require real-time on-chain tracking, wallet verification, and mark-to-market pricing aligned with HKFRS 9 and HKAS 2.
- E-Commerce Gateway Reconciliation: Drop-shipping and Amazon/Shopify ventures using payment processors like Stripe, Shopify Payments, and PayPal must reconcile rolling settlement reserves, platform processing fees, and chargeback adjustments.
- Zero-Footprint Global Founders: Managing a Hong Kong entity without local employees requires setting up clean commercial banking pathways, such as Hong Kong Bank Account Opening, ensuring that corporate transactions are properly maintained and verified for statutory audits.
Direct TCSP-Licensed Advisory vs. Unlicensed Broker Intermediaries
Many cross-border corporate services agencies act simply as unlicensed sales agents. They outsource corporate filings and audits to third-party sub-contractors, marking up service fees and creating compliance blind spots that put your company at risk.
Working directly with a primary, licensed firm protects your business:
- Verified TCSP Licensing: Olesen Global (傲承环球) operates under official Hong Kong Trust or Company Service Provider license number TC010076, fully verified with the Companies Registry.
- HKICPA Practicing Integrity: All audits are directed by practicing Hong Kong Certified Public Accountants, ensuring full compliance with the Professional Accountants Ordinance and IRD standards.
- Direct 1-on-1 Communication: Speak straight to dedicated corporate compliance specialists who manage your records in-house, preventing costly filing mistakes and data leaks.
Frequently Asked Questions: Hong Kong Profits Tax & CPA Audits
Can a Hong Kong company file a Zero Tax Return (零申报) instead of doing an annual audit?
Under the Hong Kong Companies Ordinance (Cap. 622) and Inland Revenue Ordinance (Cap. 112), any active company with banking transactions, operational income, or signed contracts must prepare audited financial statements before submitting Profits Tax Return BIR51. Filing a zero tax return without an audit when bank transactions exist constitutes tax fraud, punishable by substantial fines and prosecution under Cap. 112 Section 82.
How can I verify if an accounting service provider in Hong Kong is officially licensed?
You can search the public Register of Trust or Company Service Provider Licensees on the Hong Kong Companies Registry website. Olesen Global operates under official TCSP license TC010076, ensuring all corporate governance, accounting, and tax representation meet strict statutory compliance standards.
How long does a Hong Kong statutory tax audit take and how can I avoid late penalties?
A standard corporate statutory audit takes between 2 to 4 weeks, depending on overall transaction volume and document readiness. Working with an authorized tax representative like Olesen Global allows your company to apply for official statutory filing extensions under the IRD Block Extension Scheme, avoiding late submission penalties and arbitrary estimated assessments.
Can a dormant Hong Kong company be exempted from the annual audit requirement?
Only companies that have formally applied for and received official statutory dormant status through a special resolution filed with the Companies Registry are exempt from preparing audited financial statements under Cap. 622. An inactive company that simply has low activity without statutory dormant registration must still complete an annual audit.
Streamline Your Hong Kong Tax Filing & Statutory CPA Audit with Olesen Global
Managing Hong Kong corporate tax compliance doesn’t need to be complicated. Olesen Global delivers direct, licensed accounting, auditing, and tax filing workflows designed for global founders, Web3 innovators, and cross-border ventures.
Our 3-Step Statutory Compliance Action Path
- Step 1: Free 1-on-1 Tax Assessment — Direct analysis of your corporate structure, transaction volume, and offshore eligibility by senior compliance specialists.
- Step 2: Document & Ledger Preparation — Customized handover checklist for invoices, bank statements, and accounting ledgers to build a clear audit trail.
- Step 3: Direct CPA Audit & IRD Submission — Professional HKICPA audit execution and fast e-filing directly through authorized IRD portals.
Need immediate filing support? Book a Direct TCSP Compliance Consultation with our Hong Kong team.
Official Sources & References
- Inland Revenue Department – Profits Tax Official IRD guide to Hong Kong profits tax
- IRD – Two-tier Profits Tax Rates Official explanation of the two-tier tax rate regime
- HKICPA – Tax Practice Notes Hong Kong Institute of CPAs technical guidance on profits tax
Hong Kong Tax & Compliance Guide
- Hong Kong Profits Tax Rate 2026Now
- Hong Kong Offshore Company Setup Guide
- Annual Return Filing in Hong Kong
- Hong Kong vs. Singapore: Which is Better?
Our Related Services
Continue Reading
Ready to Register Your Hong Kong Company?
Our TCSP-licensed advisors (TC010076) are ready to help you navigate the process. Get a free consultation today.
Free Consultation