Hong Kong Bookkeeping Requirements: The Complete Compliance Guide
Operating a business in Hong Kong offers unmatched tax efficiencies and global market access. However, maintaining pristine financial records is not just a best practice—it is a strict statutory mandate. Under the Hong Kong regulatory framework, every incorporated company must keep accurate books of accounts to satisfy both tax and corporate laws.
Based on our 10+ years of corporate service data at Olesen Global, over 30% of global founders underestimate the rigor of local tax inspections. Neglecting daily ledger maintenance can quickly lead to failed audits, frozen bank accounts, and severe statutory penalties.
The Legal Framework: Section 51C and the 7-Year Record Retention Rule
Every business incorporated in Hong Kong must keep sufficient records of its income and expenditure in English or Chinese to enable its assessable profits to be readily ascertained. Under Section 51C of the Inland Revenue Ordinance (Cap. 112), failure to maintain these records without a reasonable excuse is a criminal offense that carries a maximum fine of HKD 100,000.
The law mandates that these business records must be kept for at least 7 years from the end of the relevant transaction or accounting period. This requirement applies even if the company has ceased operations or has been formally dissolved, as the Inland Revenue Department (Hong Kong) retains the right to review historical filings retrospectively.
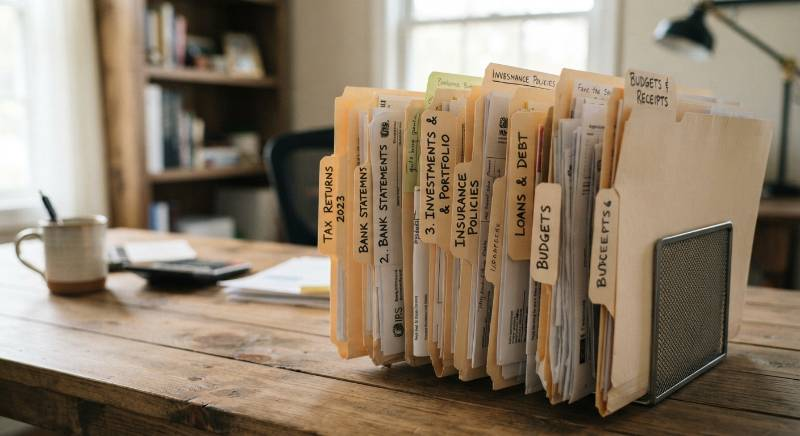
To ensure full compliance, your daily record-keeping must capture all primary financial activities. This includes receipts, bank statements, invoices, vouchers, and contracts. Use this practical checklist to verify your current document retention system:
- Income Records: Sales invoices, receipts, cash register tapes, and credit notes.
- Expense Records: Purchase invoices, supplier receipts, utility bills, and rent agreements.
- Banking Records: Monthly bank statements, deposit slips, check stubs, and remittance advices.
- Operational Ledger: General ledger, accounts receivable/payable aging reports, and inventory sheets.
- Corporate Documents: Articles of Association, board minutes, and registers maintained by your Company Secretary Services provider.
“Many international founders believe that if their company operates entirely outside Hong Kong, they are exempt from bookkeeping. This is a dangerous misconception. The Inland Revenue Department requires the same standard of record-keeping to assess and validate any offshore tax claim.”
— Senior Compliance Officer, Olesen Global
The Sovereign Ledger Framework for Global Businesses
To help international businesses navigate local regulations, we developed the Sovereign Ledger 3-Tier Framework. This methodology categorizes bookkeeping operations based on transaction volume, asset complexity, and regulatory exposure. It ensures that your business implements the exact level of internal controls required to pass an annual audit without overpaying for unnecessary administrative overhead.
We evaluate your bookkeeping requirements across three core dimensions:
- Transaction Velocity: The monthly frequency of inbound and outbound transactions, including automated payment gateway settlements.
- Asset Complexity: The presence of multi-currency accounts, inventory, intellectual property, or digital assets.
- Regulatory Exposure: Whether the company operates in a regulated sector, holds a specific license, or plans to claim offshore tax exemption.
| Tier Level | Target Business Profile | Key Bookkeeping Focus | Recommended System Setup |
|---|---|---|---|
| Tier 1: Core | Consultancies, holding companies, and early-stage startups (<50 transactions/month). | Monthly bank reconciliation, expense categorization, and basic document archiving. | Cloud-based ledger (e.g., Xero) with direct bank feeds. |
| Tier 2: Growth | E-commerce brands, SaaS providers, and global trade firms (50–500 transactions/month). | Multi-currency reconciliation, inventory valuation, and payment gateway matching. | Integrated ERP or automated bookkeeping pipelines with monthly reviews. |
| Tier 3: Enterprise | Web3 protocols, licensed financial entities, and high-volume cross-border merchants. | Digital asset pricing, gas fee tracking, intercompany transactions, and FSIE compliance. | Custom accounting architecture with dedicated daily reconciliation. |
Accounting Standards: HKFRS vs. SME-FRF & FRS
When preparing your books, your financial statements must adhere to the accounting standards issued by the HKICPA. Hong Kong maintains a dual-tier accounting framework designed to balance investor protection with administrative relief for smaller operations. Selecting the correct standard during your Accounting & Audit Services onboarding is critical for long-term compliance.
The primary standard is the Hong Kong Financial Reporting Standards (HKFRS), which is virtually identical to the International Financial Reporting Standards (IFRS). For qualifying small and medium-sized enterprises, the simpler Small and Medium-sized Entity Financial Reporting Framework and Financial Reporting Standard (SME-FRF & FRS) provides substantial relief from complex disclosure requirements.
| Comparison Dimension | Full HKFRS | SME-FRF & FRS |
|---|---|---|
| Eligibility Criteria | Mandatory for public companies, financial institutions, and large enterprises. | Private companies meeting at least two: Revenue ≤ HKD 100M, Assets ≤ HKD 100M, Employees ≤ 50. |
| Measurement Basis | Fair value accounting allowed for various financial instruments and properties. | Strict historical cost convention; no fair value adjustments or revaluations. |
| Cash Flow Statement | Mandatory inclusion in the standard financial reporting package. | Exempt; not required as part of the statutory audited accounts. |
| Deferred Tax | Requires complex calculations of temporary timing differences. | Completely exempt; no deferred tax accounting required. |
Niche Bookkeeping Scenarios: Web3, Crypto, and FSIE E-Commerce
As Hong Kong positions itself as a premier global hub for Web3 and digital assets, the local tax landscape has evolved rapidly. Standard off-the-shelf software cannot adequately handle the unique transactional nuances of decentralized finance (DeFi), smart contracts, and cross-border e-commerce operations under the Foreign-Sourced Income Exemption (FSIE) regime.
For a Web3 startup operating out of Cyberport or Science Park, bookkeeping is not just about matching bank transactions. You must account for every on-chain interaction. This includes tracking gas fees, mapping smart contract interactions, valuing volatile tokens at the exact time of receipt, and reconciling liquidity pool activities.
According to recent industry data, over 82% of Hong Kong incorporated Web3 startups fail their first major audit cycle due to undocumented gas fees and smart contract interactions. Our specialized Web3 accounting team recommends establishing clear accounting policies for token valuation and cost basis calculations early in the fiscal year.
Similarly, cross-border e-commerce merchants navigating the FSIE regime must keep detailed, segmented books. Under these rules, offshore passive income (such as interest, dividends, and IP disposal gains) may be subject to profits tax unless the company meets strict economic substance requirements. Your bookkeeping must clearly separate local trading profits from offshore passive revenues to protect your tax exemption status.
Bridging the Gap: From Bookkeeping to Audit-Ready Tax Filing
Bookkeeping is the foundation, but the ultimate goal is a successful annual audit and the submission of your profits tax return filing (Form BIR51). In Hong Kong, you cannot simply file tax returns based on un-audited books. The Companies Registry (Hong Kong) and the Inland Revenue Department require all companies to attach audited financial statements signed by a licensed CPA to their tax returns.
A structured timeline is essential to avoid late filing penalties. The Inland Revenue Department typically issues the first Profits Tax Return 18 months after the date of incorporation. Subsequent returns are issued annually in April. Depending on your financial year-end date, you may apply for an extension under the Block Extension Scheme.
| Stage | Key Activities | Typical Timeline | Deliverables |
|---|---|---|---|
| 1. Monthly Reconciliation | Categorize expenses, match bank statements, and log invoices. | Ongoing (monthly) | Trial Balance, General Ledger, and Aging Reports. |
| 2. Year-End Close | Perform physical stocktakes, calculate depreciation, and adjust accruals. | Within 1 month post year-end | Draft Financial Statements and Balance Sheet. |
| 3. External Audit | Provide supporting documents, vouchers, and contracts to the independent CPA. | 2 to 4 months post year-end | Audited Financial Statements and Auditor’s Report. |
| 4. Tax Filing | Complete Form BIR51, attach audited accounts, and submit to the IRD. | Within 1 month of receiving PTR (or extended deadline) | Submitted Profits Tax Return and Tax Computation. |
“A 2025 IRD enforcement study revealed that over 14% of audited offshore claims were rejected initially due to poor record-keeping. Proper daily bookkeeping is not an administrative burden—it is your primary defense during a tax audit.”
— Tax Partner, Olesen Global
For more details on setting up your initial corporate structure, you can read our comprehensive guide on Hong Kong Company Registration.
Why Choose a First-Hand TCSP Licensed Provider in Hong Kong
Many corporate service agencies operating online are simply unlicensed intermediaries. They outsource your sensitive financial data to third-party sub-contractors, which increases security risks, communication delays, and overall costs.
Olesen Global is a first-hand Trust and Company Service Provider (TCSP) license holder (TC010076) with a physical office in Hong Kong. This means we manage your compliance requirements directly, ensuring complete data security and professional accountability.
When you partner with us, you enjoy distinct operational advantages:
- No Middlemen: Direct access to our in-house accounting, company secretary, and tax advisory teams.
- Physical HK Presence: A local office to handle government correspondence, bank inquiries, and regulatory inspections.
- 1-on-1 Progress Tracking: A dedicated compliance officer who manages your accounts and keeps you informed at every step.
- Unified Corporate Support: Comprehensive solutions covering company formation, bookkeeping, annual audits, and trademark protection.
Frequently Asked Questions About HK Bookkeeping
Can I perform DIY bookkeeping for my Hong Kong company?
Yes, you can manage your daily bookkeeping internally using modern cloud accounting software. However, your records must still meet the professional standard required for an independent CPA audit. Most business owners find that outsourcing to a professional provider saves time and prevents costly formatting errors during the annual audit.
How does HKFRS differ from US GAAP?
HKFRS is a principles-based framework aligned with IFRS, whereas US GAAP is a rules-based system. Key differences include the treatment of inventory valuation (LIFO is not permitted under HKFRS), development costs capitalization, and the revaluation model for property and equipment. Our team can help you reconcile these systems if your parent company is based in the United States.
What happens if I miss the profits tax return filing deadline in 2026?
Missing the filing deadline can result in immediate fines ranging from HKD 1,200 to HKD 10,000, along with a double tax assessment. Prolonged non-compliance may lead to court summonses and prosecution. It is highly recommended to engage a licensed provider early to secure extensions under the Block Extension Scheme.
Do dormant companies need to maintain bookkeeping records?
Yes. Even if a company has no active operations, it must maintain basic books of accounts until it is formally deregistered or has successfully applied for official “dormant status” under the Hong Kong Companies Ordinance. Our corporate secretarial team can guide you through the process of declaring dormant status to reduce annual compliance costs.
Streamline Your Hong Kong Compliance with Olesen Global
Managing statutory compliance does not have to be a stressful distraction from growing your global business. By partnering with a licensed, first-hand professional firm, you can ensure your books remain audit-ready year-round.
At Olesen Global, we combine local expertise with a modern, client-first approach to handle your company registration, secretarial duties, and accounting needs seamlessly.
Ready to Secure Your Business Compliance?
Get in touch with our licensed Hong Kong compliance experts today for a tailored bookkeeping and audit solution.